

Everyone knows that the bank will want a home buyer to put up the property as collateral. The same goes for commercial loans. But what is collateral, exactly?
Today’s column by Marisa Said, who heads the Consumer and Microbusiness Finance Department at Bank of Valletta, continues a series of articles aimed at demystifying the world of credit.
The first two articles, on sanction letters and the difference between secured and unsecured loans, can be found here and here.
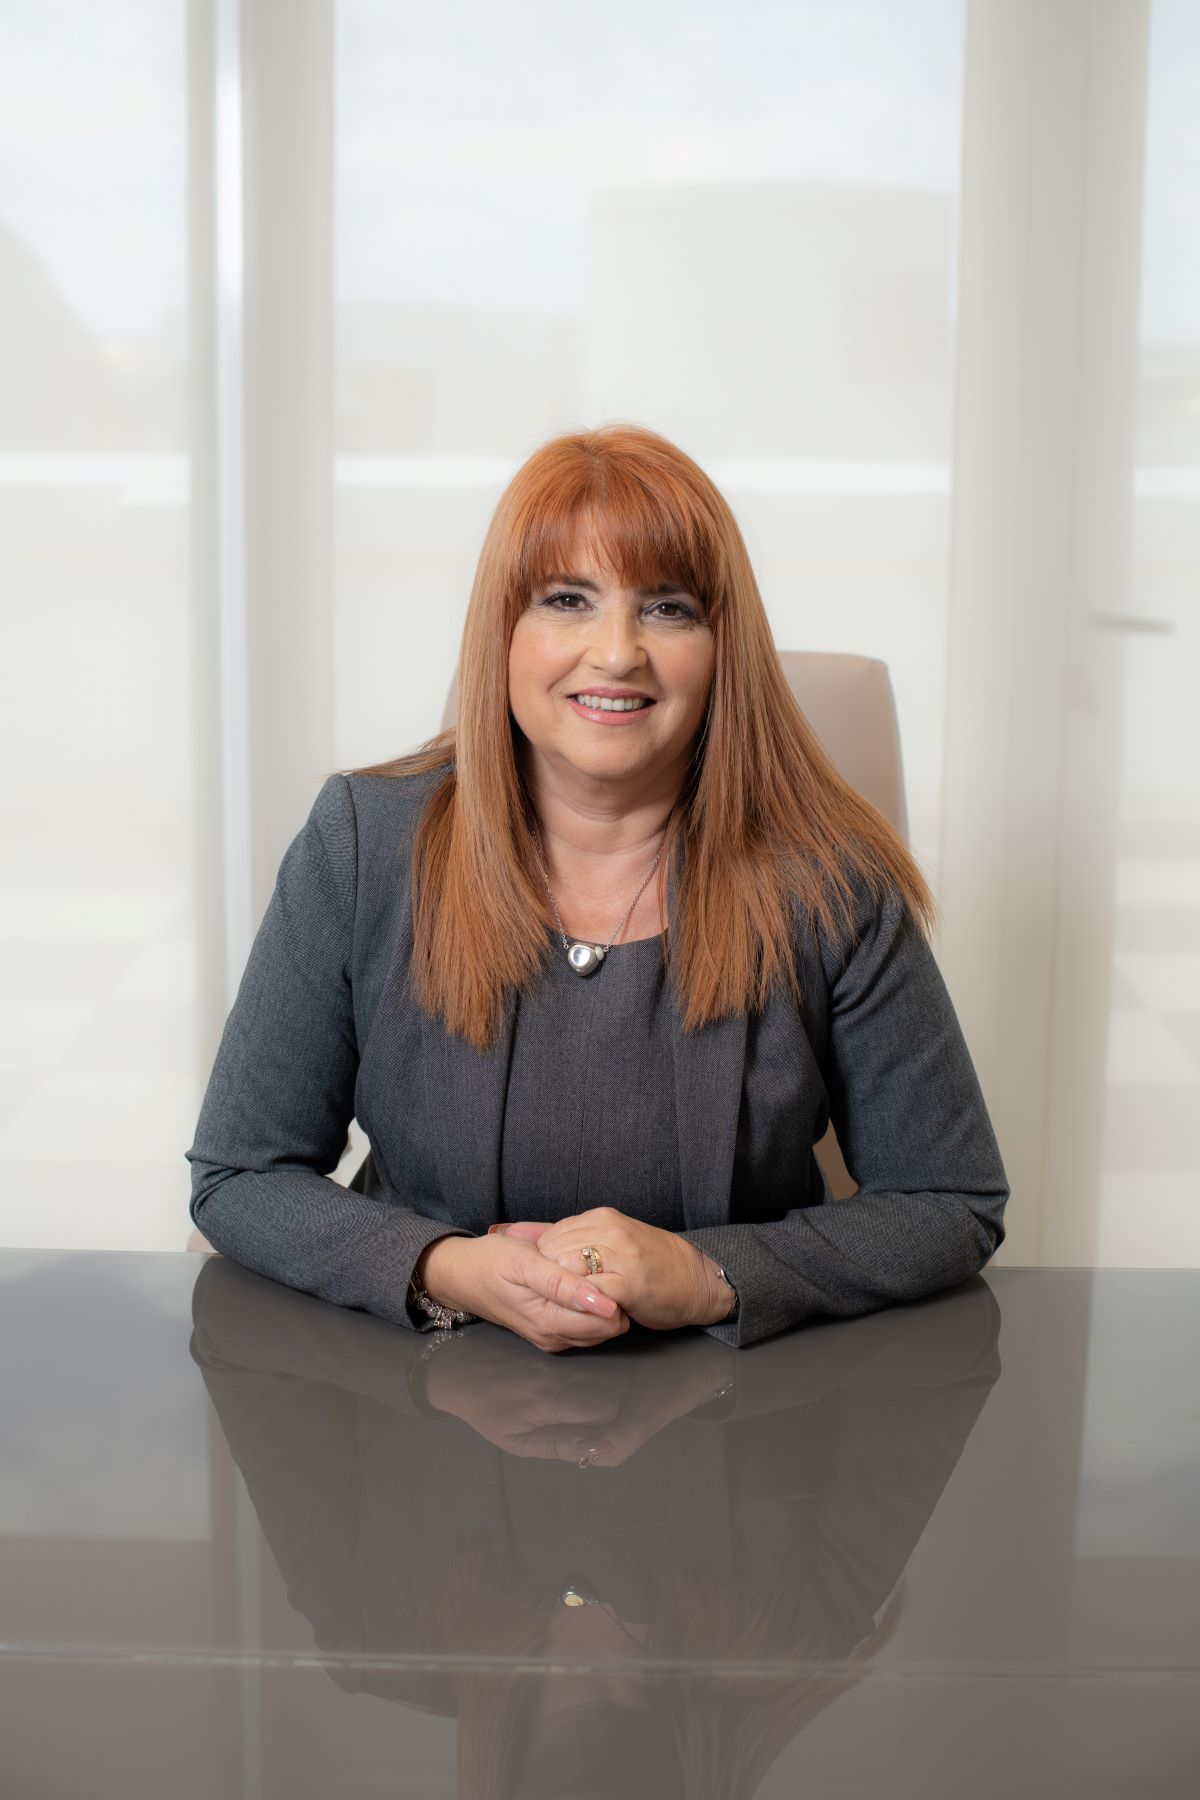
Ms Said has over 30 years of experience in retail banking, most of which are directly related to mortgages, and is a key trainer in the area of home loans.
She explains:
Collateral is an asset that a borrower places as security on a loan in case the borrower fails to repay the full loan amount to the lender.
The lender, which in most cases is usually a bank, can seize and sell the collateral to recover the money from the defaulted borrower.
Collateral can be in several forms, such as cash, real estate (property), stocks, or other typical valuable assets.
The value of the collateral must be sufficient to cover the amount of the loan. In this way, collateral reduces the lender's risk, since it is backed by a guaranteed asset, and enables the borrower to access financing at a reduced rate of interest.
In some cases, collateral might be the only viable option for a borrower to obtain a loan.
An Expert Explains is a BusinessNow.mt initiative to improve economic financial literacy by inviting industry leaders to explain technical terms in a manner that can be understood by a general audience. If you would like to suggest a term or concept for our network of professionals to break down, or if you are an expert willing to contribute to this column, send us a message on our Facebook Page.
No injuries reported as part of Valletta shop ceiling collapses
The incident occurred at 10.20am on Friday
NCPE calls for Equality Impact Assessment before TCN Budget measures come into force
'Several of the measures have the potential to increase inequality among vulnerable groups,' it said
Malta’s business conditions remain below long-term average as retail activity contracts
Malta’s business conditions remain below long-term average as retail activity contracts