

Launched in April 2025, BOV SmartPay brought the bank’s merchant acquiring services, including ePOS terminals, e-commerce payment gateways and mobilePOS solutions, under a single brand. While the products themselves were not new, bringing them together under one identity was envisaged to make it easier for merchants to access the services and support they need.
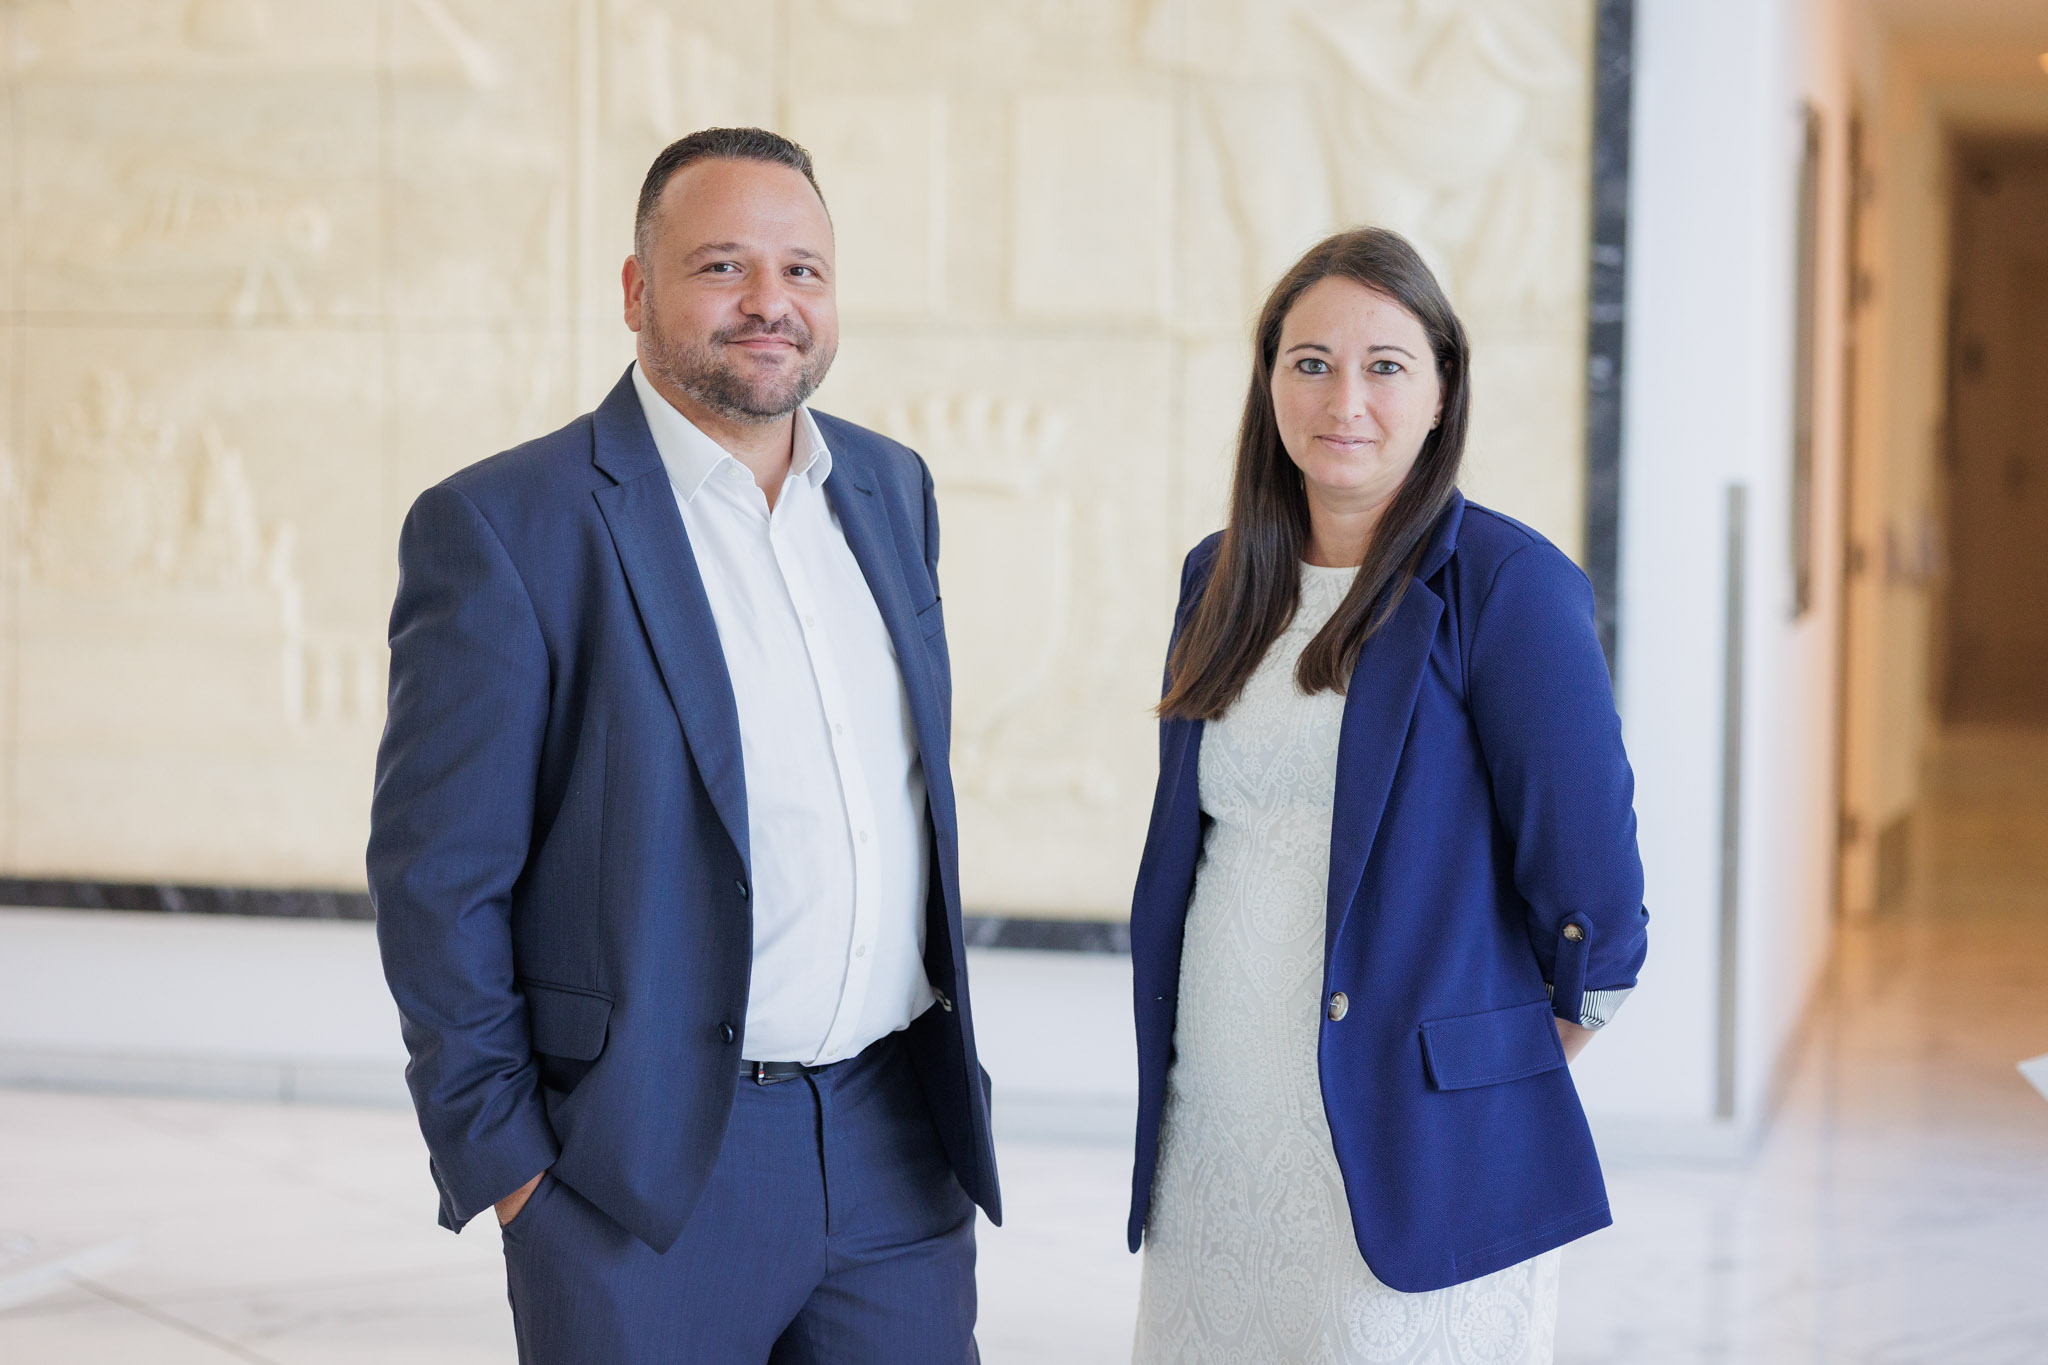
Ms Sephora Sciberras Micallef, Senior Manager within the BOV SmartPay team, oversees day-to-day operations and direct relationships with merchants. She describes a service built as much around people as products: “We wanted our merchants to be able to identify our products and know that, if they need something, they can go to BOV SmartPay directly rather than BOV in general.”
Mr Roderick Armeni, who leads business generation and sales, says that bringing the services under one brand has also made it easier for merchants to access support. “Previously, if they needed technical assistance, they had to call customer care. For anything else, they had to contact a different department. Now, everything related to our acquiring services is under BOV SmartPay.”
The more significant shift, however, is in how the team engages with merchants in the first place. Taking a proactive approach, BOV SmartPay’s sales specialists visit merchants on-site to understand their operations and recommend solutions they may not have considered. “A merchant might initially approach us for an ePOS terminal, but when we visit their premises, we can get a much better understanding of how their business operates and what other solutions might benefit them,” explains Mr Armeni.
For example, a retailer with a shop, a website and a delivery service might initially request a single terminal. A BOV SmartPay visit could reveal a broader set of requirements: an e-commerce gateway for online sales, an ePOS terminal for the shop floor and a mobilePOS solution for deliveries and on-site servicing. “By understanding the different ways a merchant does business, we can recommend a combination of integrated solutions that makes accepting payments easier across their entire operation,” he says.
MobilePOS solutions, which can be installed on a smartphone or tablet, are particularly useful for businesses operating beyond traditional shop premises. “For merchants making deliveries or providing services on-site, mobilePOS means they can accept payments directly through their phone, without needing a separate terminal,” Mr Armeni adds. The BOV SmartPay portfolio also includes a pay-by-link solution, allowing merchants to send customers a secure link to complete a payment remotely, including when collecting deposits ahead of delivery.
Both see a clear shift away from cash in Malta, although neither expects it to disappear entirely. “Card payments are increasing, and with mobile phones and smartwatches, paying has become much easier,” says Ms Sciberras Micallef. Mr Armeni adds that merchants, too, are increasingly recognising the value of electronic payments. “Merchants are realising that the time saved on handling cash, making deposits and reconciling sales can be worth more than the fees involved in accepting card payments.”
Certain sectors require more specialised support, particularly those facing a greater risk of chargebacks. “These businesses need to understand the card schemes’ rules and follow the correct procedures, so that if a dispute arises, they have the necessary documentation in place,” explains Ms Sciberras Micallef. She goes on to note that BOV SmartPay runs targeted training sessions for merchants, with specialists offering guidance tailored to the specific challenges faced by each sector.
Security is another crucial part of the service. BOV’s payment terminals comply with PCI security standards, while its systems are designed to flag potentially suspicious transactions. “We receive reports highlighting transactions that may present a security risk, and we communicate these directly to our merchants,” says Ms Sciberras Micallef, also noting that BOV is the only licensed credit institution in Malta offering acquiring services, a distinction that carries practical implications for merchants in terms of regulatory oversight, funds security and contractual clarity.
What’s more, the BOV SmartPay merchant portal provides businesses with access to transaction data that can inform how they operate day to day. Merchants can track when card payments are most frequent, monitor how sales respond to promotions and, where they operate more than one outlet, compare performance across locations. “Having this information means a merchant can see, for example, that one shop tends to be busiest in the morning and another in the afternoon, and plan accordingly,” says Mr Armeni. Investment in the portal’s analytics capabilities is ongoing, with further enhancements in development.
In an increasingly competitive payments market, BOV also sees its position as a regulated credit institution as an important distinction. Mr Armeni points to the transparency of its approach, with merchant rates published online and contractual terms clearly set out. “Merchants should know exactly what they are paying for and what they can expect from us. We want the terms to be clear and the service to be backed by the regulatory standards that apply to the bank,” he says.
Looking ahead, the BOV SmartPay team has a number of developments in the pipeline. Kiosk solutions are being further developed to meet demand from high-footfall environments, while the mobilePOS offering is being extended with updated Android software.
BOV SmartPay has certainly come a long way in just over a year, and for both Ms Sciberras Micallef and Mr Armeni, the direction of the brand will continue to be shaped by the businesses it serves. As Ms Sciberras Micallef puts it: “By listening to our merchants, understanding the challenges they face and adapting our services accordingly, BOV SmartPay can develop the right solutions and support to help them run their businesses more effectively.”
Bank of Valletta plc is a public limited company regulated by the MFSA and is licensed to carry out the business of banking in terms of the Banking Act (Cap. 371 of the Laws of Malta).
A ‘growing shortage of qualified professional heavy goods drivers’ – ATTO calls for national strategy
'This is an issue that can no longer be overlooked'
Young entrepreneurs compete with innovative business in Gozo
The ideas they showcased are aimed at addressing Gozo’s needs and opportunities

Hospital investment and energy subsidies most welcomed Budget 2027 measures, survey finds
Higher tourist accommodation charges received the most negative response