

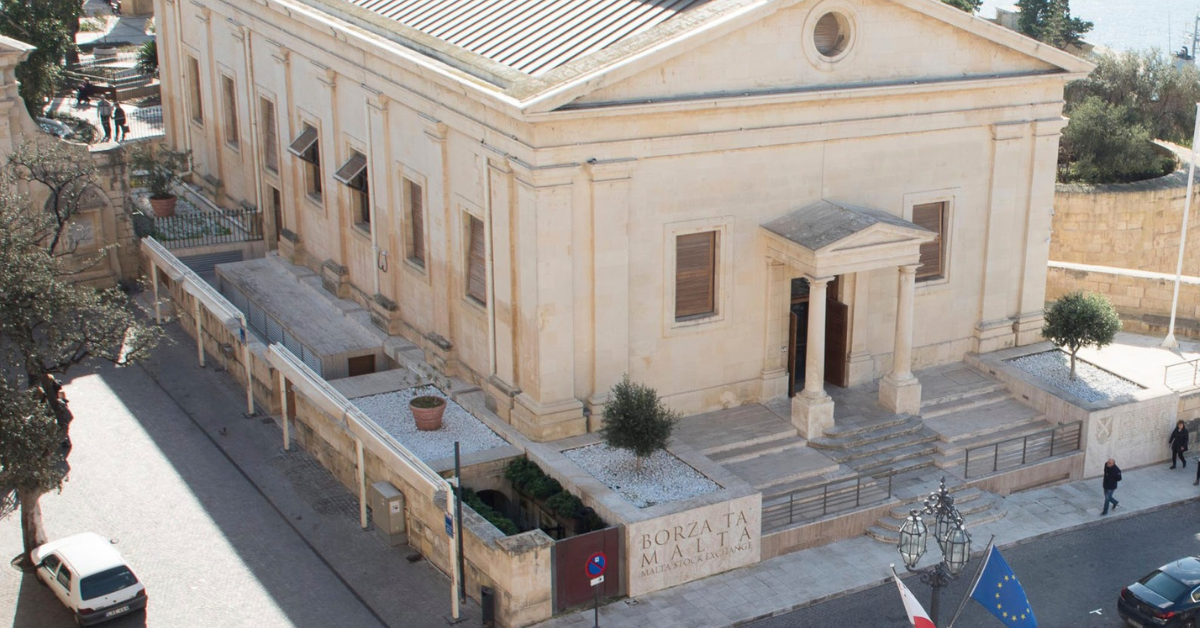
Over recent months, I regularly wrote about the need for the Government of Malta to rethink the ownership structure of the Malta Stock Exchange (MSE). Recent developments in Cyprus provide a very timely case study for policymakers in Malta especially today coinciding with the first Investor Day Conference being organized by the MSE.
Earlier this year, the Cypriot House of Representatives approved a bill providing for the privatisation of the Cyprus Stock Exchange (CSE). The Ministry of Finance in Cyprus described the vote as an important institutional and reformative step which signals a broad recognition that a small state-owned stock exchange with limited resources cannot deliver the liquidity, technology and international visibility that modern capital markets require.
It is important for policymakers in Malta to follow the progress of the privatisation of the CSE since it could provide insight into the potential appetite by larger stock exchanges into the smaller operators.
The process for the CSE privatisation
Following the passing of legislation earlier this year, the Ministry of Finance is now expected to issue an international tender for the privatisation of the CSE. The Cypriot government is not simply looking for a passive shareholder, but one that can run and expand the operations of the CSE.
In recent weeks, the international press indicated possible interest by two operators in particular. The Tel Aviv Stock Exchange (TASE), which became a publicly traded company in Israel in 2019, is reportedly examining a bid for the CSE as it is attracted by its EU operating licence giving the TASE a potential direct foothold in the euro area. Moreover, Euronext, which acquired the Athens Stock Exchange last year and already shares a trading and clearing platform with Cyprus dating back to 2006, is also widely seen as a natural contender.
Some media commentators have clearly stated that despite the size of the CSE, a small exchange with an EU licence can be seen as a strategic asset.
The benefits of privatisation
The Cypriot authorities argued that the sale to a strategic investor would improve the exchange’s ability to attract new listings and would bring more investment from both domestic and international institutions as well as individual investors.
The government’s aim is to transform the CSE into a competitive regional capital markets centre. The Cypriot authorities are mindful that international investors are willing to engage with a small capital market once it has the right access and infrastructure in place.
The possible solution for the MSE
The process taking place in Cyprus could be an important eye-opener for Malta highlighting the pace of consolidation among European stock exchanges.
In my view, the Government of Malta should consider divesting a minimum of 80 per cent of its shareholding in Malta Stock Exchange plc through a three-pronged process:
1. the introduction of a strategic investor – ideally an established international exchange group selected through a competitive international tender;
2. the participation of MSE member firms in order to align the interests of market participants with the long-term success of the exchange together with other financial investors, including international financial institutions to help in the internationalisation efforts of the Maltese equity market; and
3. an Initial Public Offering on the MSE’s own Regulated Main Market, enabling the Maltese investing public to become direct owners of the exchange.
The structure would be similar to the privatisation of the Boursa Kuwait in 2019 in which the Athens Stock Exchange acquired a 44 per cent stake, followed by an IPO of 50 per cent of the shares, with the government retaining 6 per cent.
The main objective should be to extend the reach of the MSE by having a strategic partner with a business development mindset geared towards regular engagement with international institutional investors and to improve custody links for enhanced international investor participation. Moreover, this would be an excellent opportunity to hopefully kickstart the moribund primary equity market in Malta and allow investors to participate in the success and future growth of the MSE.
The MSE has indeed been increasing its level of profitability in recent years and as such, the Government should achieve a reasonable sum from the disposal of its stake.
Setting up a capital markets development fund
The proceeds from the MSE privatisation should not be absorbed into the Government Consolidated Fund but directed towards the setting up of a dedicated Capital Markets Development Fund (CMDF).
Initially, these funds can be used to introduce Savings and Investment Accounts (SIAs) in Malta by, for example, providing added tax incentives on investment income to the ‘prescribed funds’ being managed by local credit institutions and other investment providers. In recent years, these investment products have failed to attract substantial inflows as appetite for Malta-based investments weakened. The objective would be for these prescribed funds to be recognised as a Maltese SIA subject to an annual subscription limit per investor. This will be of great help to the asset management companies running these funds as they should increase in popularity and the growth in the assets under management will largely be diverted into the Maltese capital markets.
Additionally, the CMDF could help finance a Government contribution or bonus into these funds for first-time investors, particularly young people (similar to the recent initiative in Greece), to encourage a shift from bank deposits towards long-term investment.
In essence, a privatised stock exchange with a strategic international partner should increase the attractiveness and liquidity of the market, while SIAs would mobilise the substantial domestic savings currently held in bank deposits into investment opportunities. Financing the incentives through the sale proceeds of the MSE would enable Government to support the objectives of the Savings and Investments Union without adding pressure on public finances.
As the consolidation of Europe stock exchanges accelerates, Malta risks being left behind if it does not act with similar determination to the authorities in Cyprus, at a time when the pool of potential strategic partners interested in acquiring a small EU exchange may be limited. Unfortunately, the Budget Speech earlier this week once again failed to articulate a vision for the capital market.
The privatisation and IPO of the MSE could truly mark a decisive turning point for the development of the Maltese capital market.
The article contains public information only and is published solely for informational purposes. It should not be construed as a solicitation or an offer to buy or sell any securities or related financial instruments. No representation or warranty, either expressed or implied, is provided in relation to the accuracy, completeness or reliability of the information contained herein, nor is it intended to be a complete statement or summary of the securities, markets or developments referred to in this article. Rizzo, Farrugia & Co. (Stockbrokers) Ltd (“Rizzo Farrugia”) is under no obligation to update or keep current the information contained herein. Since the buying and selling of securities by any person is dependent on that person’s financial situation and an assessment of the suitability and appropriateness of the proposed transaction, no person should act upon any recommendation in this article without first obtaining investment advice. Rizzo Farrugia, its directors, the author of this article, other employees or clients may have or have had interests in the securities referred to herein and may at any time make purchases and/or sales in them as principal or agent. Furthermore, Rizzo Farrugia may have or have had a relationship with or may provide or has provided other services of a corporate nature to companies herein mentioned. Stock markets are volatile and subject to fluctuations which cannot be reasonably foreseen. Past performance is not necessarily indicative of future results. Foreign currency rates of exchange may adversely affect the value, price or income of any security mentioned in this article. Neither Rizzo Farrugia, nor any of its directors or employees accepts any liability for any loss or damage arising out of the use of all or any part of this article.
The move to T+1 settlement
The settlement cycle in Europe had already changed before when in October 2014, European markets collectively moved from T+3 to ...
From property to the stock market
The composition of household wealth locally remains heavily tilted towards real estate with very limited exposure to capital markets
What is driving the dollar’s strength?
The US Dollar ended the third quarter of 2026 with its sixth consecutive quarterly gain